Publushed 15/04/2025
Time to read 8 minutes
Chargeback Trends in 2026: What's Driving Disputes Now
A chargeback happens when a cardholder asks their bank to reverse a payment, and it matters because merchants can lose revenue, banks take on more risk, and shoppers expect fair, fast protection when something goes wrong. In 2026, chargeback pressure is rising as digital payments grow, fraud tactics get smarter, and card network rules keep tightening.
That mix is changing how disputes start, how they're reviewed, and why more businesses are getting caught off guard. You'll see what's shifting, why disputes are rising or changing shape, and what companies can do now to protect both income and customer trust.
What is driving chargebacks higher in 2026
Chargebacks are climbing because more sales now happen in places where the card and buyer are harder to verify. At the same time, more orders involve subscriptions, digital goods, marketplaces, and cross-border shipping, all of which create extra room for confusion.
Just as important, not every dispute starts with stolen card data. Many begin with a late package, a billing descriptor a customer doesn't recognize, or a buyer who skips support and calls the bank first. That mix is pushing dispute volume up across industries.
Card not present sales keep creating more dispute risk
When a shopper buys online, in an app, through social commerce, or from a mobile wallet, the merchant doesn't see the physical card. That gap matters. In-store payments still have fraud risk, but card-not-present sales remove a simple layer of proof that often helps stop bad transactions before they happen.
Faster checkout has made buying easier, and that's great for conversion. Yet speed can cut both ways. If a checkout flow asks for very little, stores may win more orders but also invite more fraud, more accidental purchases, and more post-purchase confusion.
This shows up in a few common ways:
- A one-tap mobile purchase gets approved, but the buyer later doesn't recognize the charge.
- A social commerce order looks simple at checkout, yet shipping details, seller identity, or refund terms are easy to miss.
- An app-based purchase, especially for digital goods, can happen in seconds, which leaves little time for review.
- A marketplace sale adds another layer because the customer may not know who actually billed them or who must handle the refund.
Cross-border transactions raise the risk even more. Currency conversion, longer delivery times, customs delays, and language gaps all make disputes more likely. So even when there is no true fraud, a poor handoff after checkout can still end in a chargeback.
The sale may feel finished at checkout, but most disputes start after the payment goes through.
First party misuse is still a major reason for chargebacks
A large share of disputes still comes from friendly fraud, although many teams now call it first-party misuse or consumer dispute abuse. In plain language, it means the real cardholder made the purchase, or someone in their household did, but the charge still gets disputed with the bank.
The most common patterns are easy to spot:
- A customer forgets about a recurring plan and disputes the renewal.
- A child, spouse, or other family member makes a purchase, but the main cardholder doesn't recognize it.
- A buyer receives the item, then claims it never arrived.
- A shopper wants a faster result and goes straight to the bank instead of asking for a refund first.
Digital goods make this worse because delivery is instant and hard to "see" later. Marketplace sales add confusion because the storefront, seller, and payment descriptor may all look different. If support is slow, return rules are unclear, or shipping updates are weak, customers often take the path that feels easiest. Too often, that's the dispute button.
The biggest chargeback trends businesses should watch this year
The chargeback story in 2026 is not just about more disputes. It's about faster disputes, smarter fraud, and higher proof standards. That puts pressure on every part of the business, from checkout and support to billing and back-office review.
AI is helping both fraud teams and fraudsters
AI is now part of the chargeback fight on both sides. For merchants, that can be a real win. Risk tools can flag odd order patterns, compare behavior against past fraud, and sort cases by urgency before a human ever opens the file.
AI can help teams:
- Spot unusual order velocity
- Detect mismatched identity signals
- Prioritize likely first-party misuse
- Pull dispute records together faster
That said, fraudsters are using the same kind of speed. They can scale phishing emails, build more believable fake identities, and test account takeover attempts in ways that look less random than old-school fraud.
AI can shrink the workload, but it can't replace judgment.
Networks and issuers are pushing for better evidence and faster responses
Card networks and issuers keep refining how disputes move through the system. Reason codes shift, evidence standards change, and response windows stay tight. That means winning chargebacks is less about arguing harder and more about submitting the right proof, in the right format, on time.
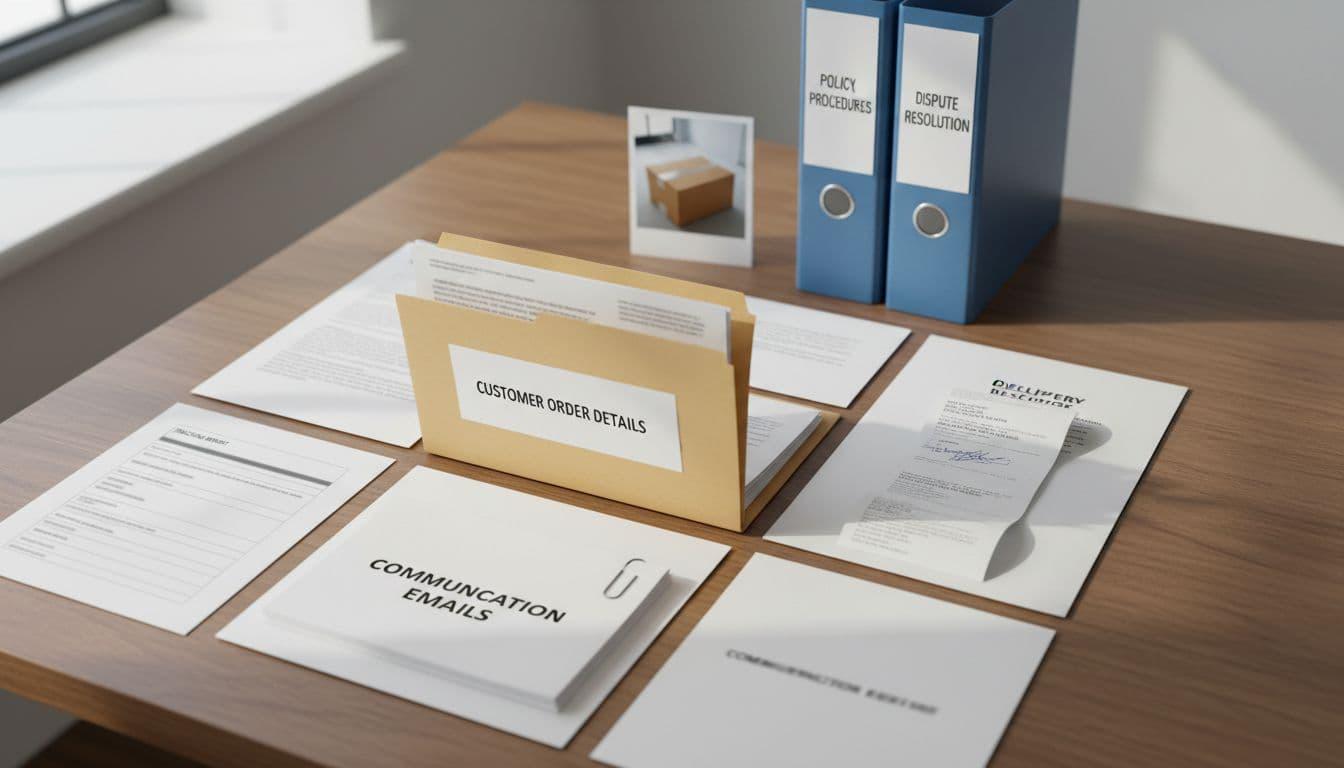
The evidence that keeps gaining value is simple and concrete:
- Clear order details, including item, amount, and date
- Delivery proof or service-use records
- Customer communication logs
- Refund or cancellation history
- Billing descriptors that match the brand the shopper knows
Subscription and recurring payments are getting more scrutiny
Recurring billing keeps driving chargebacks because customers notice these charges differently. A one-time purchase can fade from memory, but a renewal that shows up unexpectedly often feels personal. When trial terms are fuzzy, cancel options are hard to find, or the billing descriptor looks unfamiliar, the dispute risk jumps fast.
The best subscription programs remove friction in the right places:
- Show trial terms and renewal timing before checkout.
- Send a clean receipt after sign-up and after renewal.
- Make account access and cancellation easy to find.
- Use support to solve billing confusion before it becomes a dispute.
How chargebacks are changing across industries in 2026
Chargeback trends don't look the same in every sector. The common thread in 2026 is customer confusion after payment, not just fraud at checkout.
Ecommerce and marketplaces
For ecommerce brands, two of the biggest dispute reasons are still item not received and item not as described. Marketplaces add another layer: the shopper may buy on one site, get fulfillment from another seller, and see a billing name they don't know.
SaaS, streaming, and digital services
Digital businesses face a different kind of chargeback pressure. The product arrives right away, or it never arrives in a physical sense at all, so the argument usually shifts to billing, access, and terms. In 2026, recurring disputes keep rising when customers move from a free trial to a paid plan and feel caught off guard.
Travel, events, and high-ticket services
Travel, ticketing, and high-ticket services still run into chargebacks because plans change after the sale. Partial refunds, rebooking credits, and date changes are major flashpoints. Customers need clear terms before purchase and plain updates after purchase. In these sectors, silence is expensive.
Share this post
Recommended articles
© 2026 Payments Lab Ltd. All rights reserved.
© 2026 Payments Lab Ltd. All rights reserved.