Publushed 20/03/2025
Time to read 6 minutes
How to Set Up a Merchant Account in 2026 Without Delays
A merchant account lets your business accept card payments and move the money into your bank account. Behind the scenes, it works with a payment processor, a payment gateway, and your business checking account, like a relay team passing the payment from customer to bank.
In 2026, setup feels a bit stricter because providers look closely at risk. They review your industry, chargeback history, fraud controls, refund rules, and even how your checkout works. That extra review can feel annoying, but it also explains why some applications move fast while others stall.
Make sure your business is ready before you apply
A merchant account application isn't hard, but it does reward clean details. Think of it like applying for a lease. If your paperwork matches and your story makes sense, the process goes faster.
Know what providers check during underwriting
Underwriting is the provider's risk review. In plain English, they're asking one thing: "Does this business look likely to process legitimate sales without too many disputes or losses?"
They usually check your business type, how you sell, your average ticket size, and your monthly card volume. They also look at refund rates, delivery timelines, prior processing history, and sometimes the owner's credit. If you run a higher-risk model, such as subscriptions or pre-orders, they may ask more questions.
The fastest way to get flagged is to describe your business too loosely or leave out part of your sales model.
Gather the documents you will usually need
Most providers ask for the same core items. Have them ready before you apply, because missing documents slow everything down.
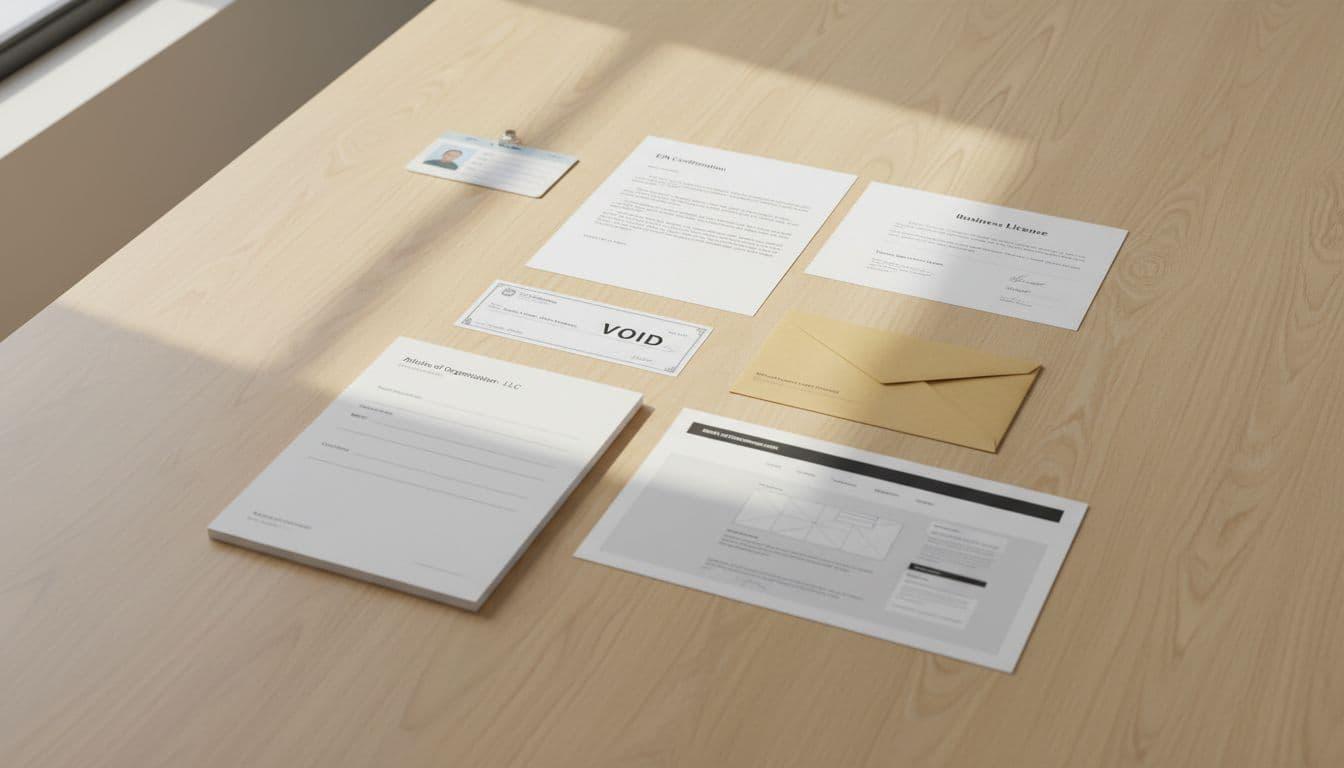
- EIN and business formation documents
- Business license, if your state or city requires one
- Business bank account details
- Government-issued photo ID
- Voided check or bank letter
- Website URL, pricing, refund policy, and shipping policy
- Recent processing statements, if you're switching providers
Online businesses often need a live website before approval. A half-built store with no policies is like opening a shop with no front door. Even a simple site works better than a blank page.
Choose the right merchant account provider for how you sell
Not every payment provider fits every business. Some are built for speed. Others are built for lower long-term cost, better support, or higher-risk industries. The right pick depends on how you take payments every day.
Compare merchant accounts, payment service providers, and high-risk specialists
A dedicated merchant account gives your business its own processing relationship. That often means more account stability, more room to grow, and better pricing once volume rises.
A payment service provider bundles everything into one account structure. It's often faster to start, which helps new businesses. Still, these platforms can be stricter with sudden volume spikes, unusual orders, or industries they don't like.
High-risk specialists serve businesses that regular providers avoid or price aggressively. That includes travel, supplements, adult, CBD, and many subscription models. If your business falls into one of those groups, starting with a specialist can save time.
Look past the headline rate and check the full fee structure
The advertised rate is rarely the full story. Ask for a complete fee schedule and, if possible, a sample statement. Key fees to check:
| Fee type | What it means |
|---|---|
| Interchange-plus | Card cost plus provider markup |
| Flat-rate | One set rate for each transaction |
| Monthly fee | Ongoing account or platform charge |
| Gateway fee | Cost for online payment gateway access |
| PCI fee | Charge for PCI program or compliance tools |
| Chargeback fee | Cost when a customer disputes a payment |
| Refund cost | Fee kept or charged when you refund |
| Early termination fee | Charge for leaving before contract end |
| Reserve | A portion of funds held back for risk |
The takeaway is simple: the cheapest rate on a sales page may not be the lowest real cost on your statement.
Set up your merchant account step by step
Once you're approved, the last mile begins. This is where small setup choices can prevent failed payments, fraud issues, and chargebacks later.
Submit the application and answer risk questions clearly
Fill out the application using matching legal and banking details. Your business name, tax information, and bank account should line up exactly with your records.
Be clear about what you sell, when you bill, how you deliver, and how refunds work. Mention every sales channel, including online, in-person, phone, or invoice payments. Vague descriptions are a common reason applications stall.
Connect your website, checkout, and bank account
After approval, connect your payment gateway or hosted checkout to your site. Run a few test transactions before going live. Also confirm your site has SSL security, your checkout loads properly on mobile, and your settlement bank account is linked correctly.
Turn on security and chargeback protection from day one
Fraud tools shouldn't be an afterthought in 2026. Turn on AVS, CVV checks, and 3D Secure where supported. If your provider offers device checks or velocity rules, use them.
Clear billing descriptors also help because customers are less likely to dispute a charge they recognize. Add visible customer service contact details, a simple refund policy, and order tracking for shipped items.
Setting up a merchant account in 2026 isn't hard, but sloppy prep can make it feel that way. When your documents are ready, your provider matches your sales model, and your fraud settings are active, the process gets much smoother. A solid merchant account setup doesn't only help you get approved, it helps you get paid with fewer surprises.
Share this post
Recommended articles
© 2026 Payments Lab Ltd. All rights reserved.
© 2026 Payments Lab Ltd. All rights reserved.